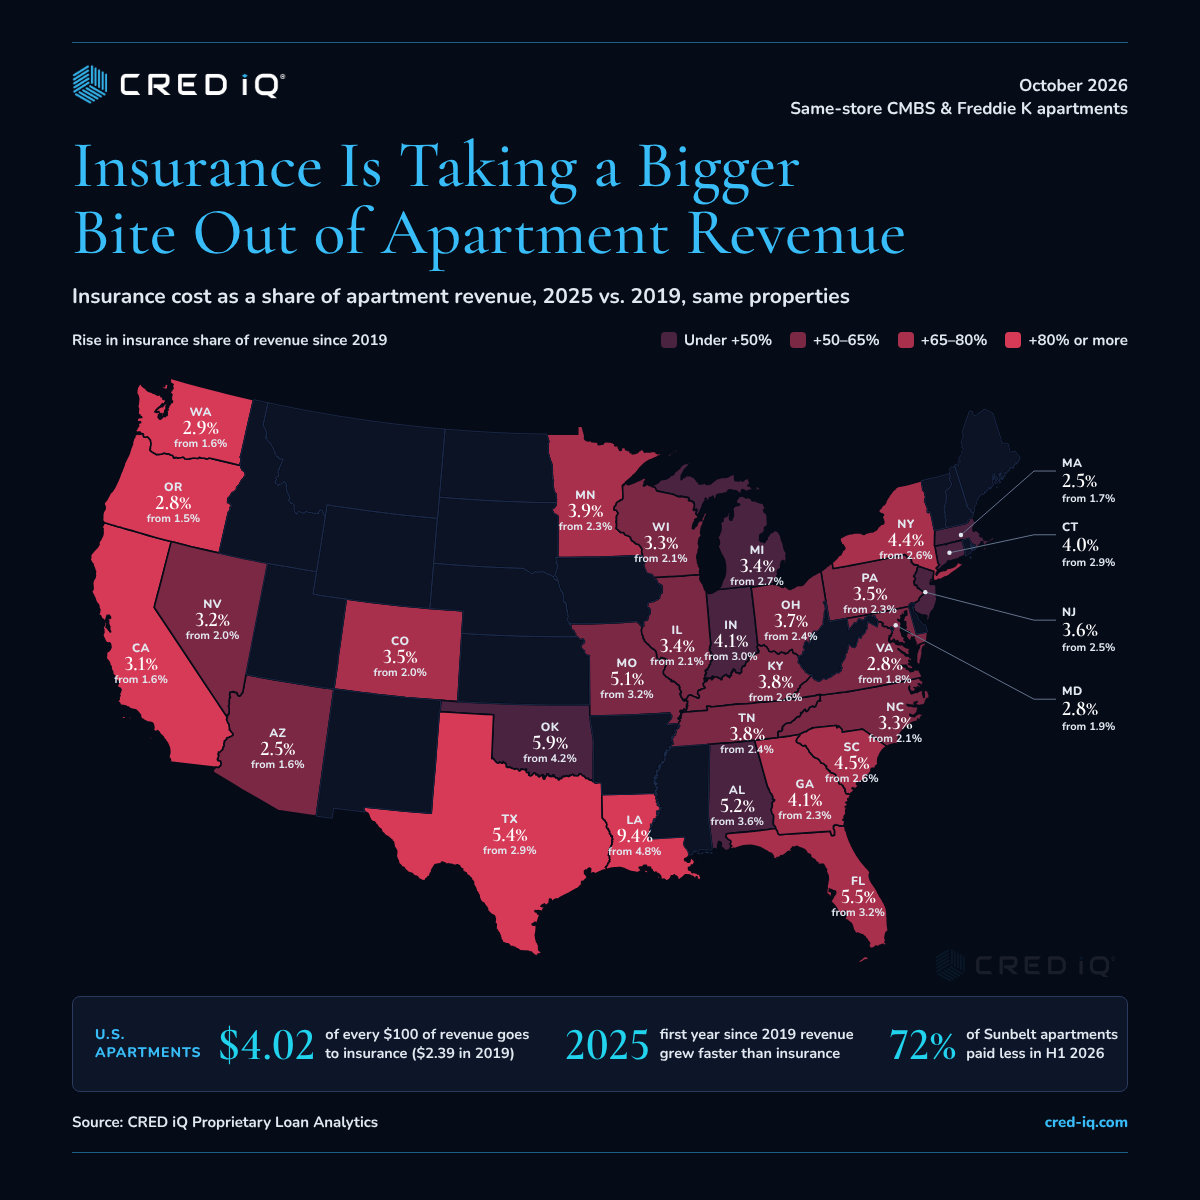
In 2019, a Louisiana apartment property financed in a CMBS or Freddie K deal spent about $4.77 on insurance for every $100 of revenue it collected. By 2025, that figure was $9.42, and that is after premiums fell last year.
That is the shape of the apartment insurance story. After five straight years of increases, insurance costs on apartment properties fell 2.2% in 2025, according to CRED iQ’s same-store analysis of property operating statements. That followed a 28.5% jump in 2023. But the relief came off a much higher base: apartment insurance costs are still more than double their 2019 level.
The pressure has clearly eased. In 2023, 46% of apartment properties saw their premiums rise more than 20%. In 2025, 24% did, and 36% paid less than the year before.
The Sunbelt Turned First
The markets with the sharpest run-up are the ones now getting relief. Florida apartment premiums rose 2.5-fold between 2019 and 2024, including a 46% jump in 2023 alone. In 2025 they fell 9.8%. Texas apartments fell 8.4% and Louisiana apartments 10.5%. Nearly two-thirds of Florida apartment properties paid less than a year earlier, as did 57% in Texas and 58% in Louisiana.
The decline has continued into 2026. In the first half of the year, 59% of apartment properties paid less for insurance than in the first half of 2025, up from 38% a year earlier. In the Sunbelt, 72% paid less, and the typical premium fell 11%.
| 2023 | 2024 | 2025 | |
|---|---|---|---|
| Louisiana apartments | 262 | 265 | 237 |
| Florida apartments | 239 | 255 | 230 |
| Texas apartments | 231 | 243 | 223 |
| California apartments | 205 | 236 | 251 |
| New York apartments | 166 | 192 | 201 |
| Sunbelt apartments | 223 | 239 | 221 |
| Coastal metro apartments | 187 | 216 | 226 |
| All apartments | 199 | 220 | 215 |
The Coasts Are Still Climbing
Coastal apartment owners have not shared in the relief. Premiums on apartments in major coastal metros rose 4.8% in 2025, and California apartments rose 6.3%. California has now passed Florida on cumulative growth since 2019, with an index of 251 against Florida’s 230, and coastal apartments overall (226) have passed the Sunbelt (221).
Rents Never Kept Up
The bigger problem for owners is that revenue did not keep pace. On the same properties, apartment revenue per unit rose 27% from 2019 to 2025, from $14,210 to $19,292 a year. Insurance per unit rose 115%, from $339 to $778. Nationally, insurance now takes $4.02 of every $100 of apartment revenue, up from $2.39 in 2019. Insurance outran rent in every one of the 30 states we measured, led by Louisiana, California, Oregon, Washington and Texas.
| State | 2019 | 2025 | Change |
|---|---|---|---|
| Louisiana | $4.77 | $9.42 | +97% |
| California | $1.63 | $3.12 | +91% |
| Oregon | $1.49 | $2.77 | +86% |
| Texas | $2.92 | $5.37 | +84% |
| Washington | $1.60 | $2.95 | +84% |
| Georgia | $2.34 | $4.07 | +74% |
| Florida | $3.21 | $5.55 | +73% |
| New York | $2.60 | $4.37 | +68% |
| Michigan | $2.71 | $3.39 | +25% |
| United States | $2.39 | $4.02 | +68% |
2025 Was a Turning Point
Last year was the first since 2019 in which apartment revenue grew faster than insurance: revenue rose 1.4% while insurance costs fell about 2%. In the Sunbelt, apartment revenue was flat, but insurance fell 7.2%, or $65 million. As a result, net operating income fell 1.4% instead of 2.1%.
For lenders, the Sunbelt relief is real and arrives as loans head toward 2027 and 2028 refinancings. But insurance costs for Sunbelt apartments are still more than double their 2019 level, and on the coasts they are still rising. The spike is over. The higher costs stayed.
Source: CRED iQ proprietary loan-level analytics, October 2026. Same-store analysis of property operating statements for apartment properties securing CMBS and Freddie K loans: each year compares the same properties’ annual insurance cost and revenue with the prior year, chained to 2019 = 100. 2025 and first-half 2026 figures are preliminary.
