When a $48.0 million loan on Euclid Apartments in Euclid, Ohio, was split across four conduit deals in 2024, the property was appraised at $77.0 million. In April 2026, a new appraisal put it at $18.1 million, 76% less. The loan went to special servicing in February 2025 for payment default. A court-appointed receiver now runs the property, which was 33% occupied in the latest report, and the special servicer has a default judgment against the guarantor.
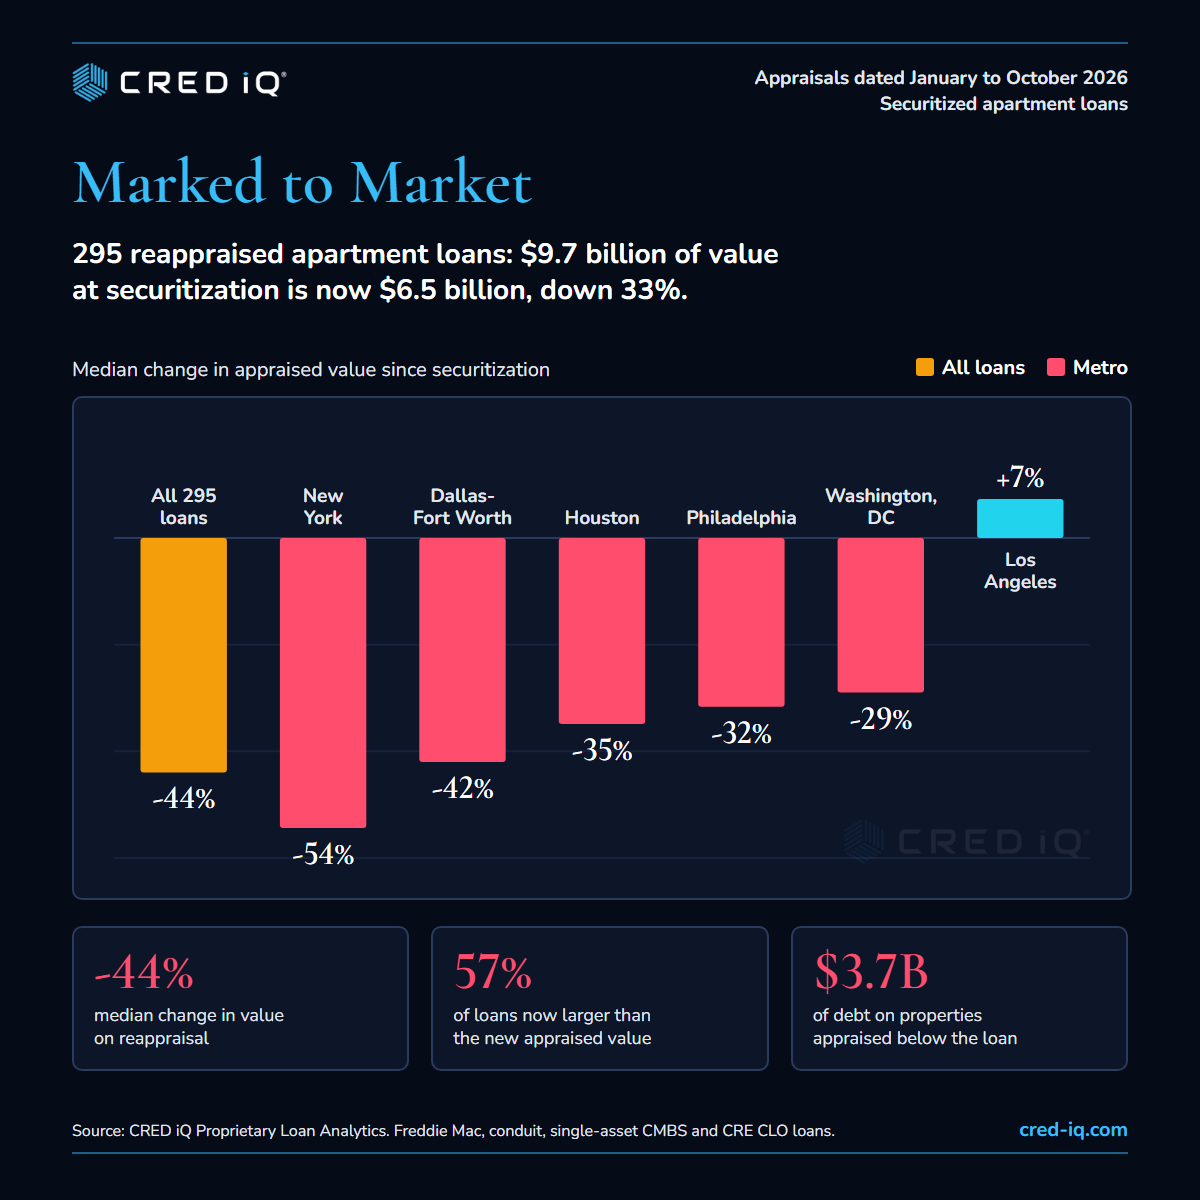
Euclid is an extreme case, but the direction is common. CRED iQ tracked 295 securitized apartment loans, in Freddie Mac, conduit, single-asset and CRE CLO deals, that received a new appraisal between January and October 2026. At securitization the properties were valued at $9.7 billion. The new appraisals put them at $6.5 billion, down 33%. The median loan’s property lost 44%, and 57% of the loans, carrying $3.7 billion of debt, now exceed the new value.
Appraisals Follow Trouble
Servicers order new appraisals when loans get into trouble, and 92% of these loans were delinquent or with the special servicer in their latest report. These figures describe distressed apartments, not the whole market. The 23 performing loans that were reappraised came in higher, with a median gain of 24%. For the 272 distressed loans, the median property lost 45%, and the loan-to-value ratio went from 63% at securitization to 101%.
| Deal type | Loans | Value at securitization ($B) | 2026 appraisal ($B) | Change | Median change | Loans now underwater |
|---|---|---|---|---|---|---|
| Freddie Mac | 211 | 3.72 | 2.47 | -33% | -49% | 62% |
| Conduit CMBS | 68 | 3.01 | 2.05 | -32% | -33% | 38% |
| Single-asset CMBS | 10 | 2.61 | 1.71 | -35% | -41% | 80% |
| CRE CLO | 6 | 0.38 | 0.28 | -27% | -28% | 67% |
| All reappraised loans | 295 | 9.71 | 6.50 | -33% | -44% | 57% |
New York’s Small Buildings Took the Deepest Cuts
The New York metro area accounts for 130 of the loans. The median New York property lost 54% of its value, and 74% of the loans are now underwater. Most are small: the median building has about 22 units and a $4.6 million loan, 105 are in Freddie Mac small-balance deals, and 83 were securitized in 2019. Outside New York, the median loss was 33%.
Texas follows: the median reappraisal was down 42% in Dallas-Fort Worth and 35% in Houston. Freddie Mac floating-rate loans from 2022 were hit hard. Jerome in Glendale, Arizona, fell to $62.5 million from $137.0 million, and The Kace in Grand Prairie, Texas, to $82.9 million from $155.4 million. Los Angeles was the only large metro where the median value rose.
Big loans are not spared. Parkhill City and 89th Avenue in Queens, a $225.0 million single-asset loan, was appraised at $178.6 million in March 2026, against $322.5 million in 2021. Parkmerced in San Francisco was valued at $1.43 billion in February 2026, below the $1.46 billion of debt on the property and down from $2.11 billion in 2019.
New Loans, Old Problem
Recent vintages have held up no better. The 45 reappraised loans from deals issued in 2023 through 2026 lost 39% of their value in aggregate, and their loan-to-value ratio rose from 62% to 101%. Park at Trowbridge in Southfield, Michigan, appraised at $73.0 million for a 2023 conduit deal, was valued at $19.4 million in June 2026, below its $28.8 million loan.
| Property | Market | Deal type | Loan ($M) | Value at securitization ($M) | 2026 appraisal ($M) | Change |
|---|---|---|---|---|---|---|
| Euclid Apartments | Euclid, OH | Conduit CMBS | 48.0 | 77.0 | 18.1 | -76% |
| Park at Trowbridge | Southfield, MI | Conduit CMBS | 28.8 | 73.0 | 19.4 | -73% |
| Jerome | Glendale, AZ | Freddie Mac | 74.9 | 137.0 | 62.5 | -54% |
| The Kace | Grand Prairie, TX | Freddie Mac | 92.2 | 155.4 | 82.9 | -47% |
| Parkhill City and 89th Avenue | Queens, NY | Single-asset CMBS | 225.0 | 322.5 | 178.6 | -45% |
| Parkmerced | San Francisco, CA | Single-asset CMBS | 1,460.0 | 2,110.0 | 1,430.0 | -32% |
The Takeaway
Delinquency rates show which apartment loans are in trouble. Reappraisals show what is left. The median loss on these loans, 44%, is larger than the equity cushion they started with at a 63% loan-to-value ratio. With $3.7 billion of debt now above the appraised value, the new number, not the one in the offering documents, is where any workout starts.
Source: CRED iQ proprietary loan-level analytics, November 2026. Multifamily loans in Freddie Mac, conduit, single-asset/single-borrower and CRE CLO securitizations with a new appraisal dated January through October 2026, compared with the appraised value at securitization; split and pari passu notes are combined into one loan. Distressed = delinquent, including loans past maturity, or in special servicing. October figures are preliminary.
