Industrial, hospitality, retail, and self storage post $4.6 billion in new distress
The CRED iQ distress rate bottomed at 10.11% in April and rose for three consecutive months, reaching 10.78% in July. The special servicing rate followed the same pattern, climbing from 9.73% to 10.02% over that stretch, and the delinquency rate moved from 8.08% to 8.67%. Early August figures point to a fourth straight increase across all three measures, though the month is still being finalized.
Property Type Analysis
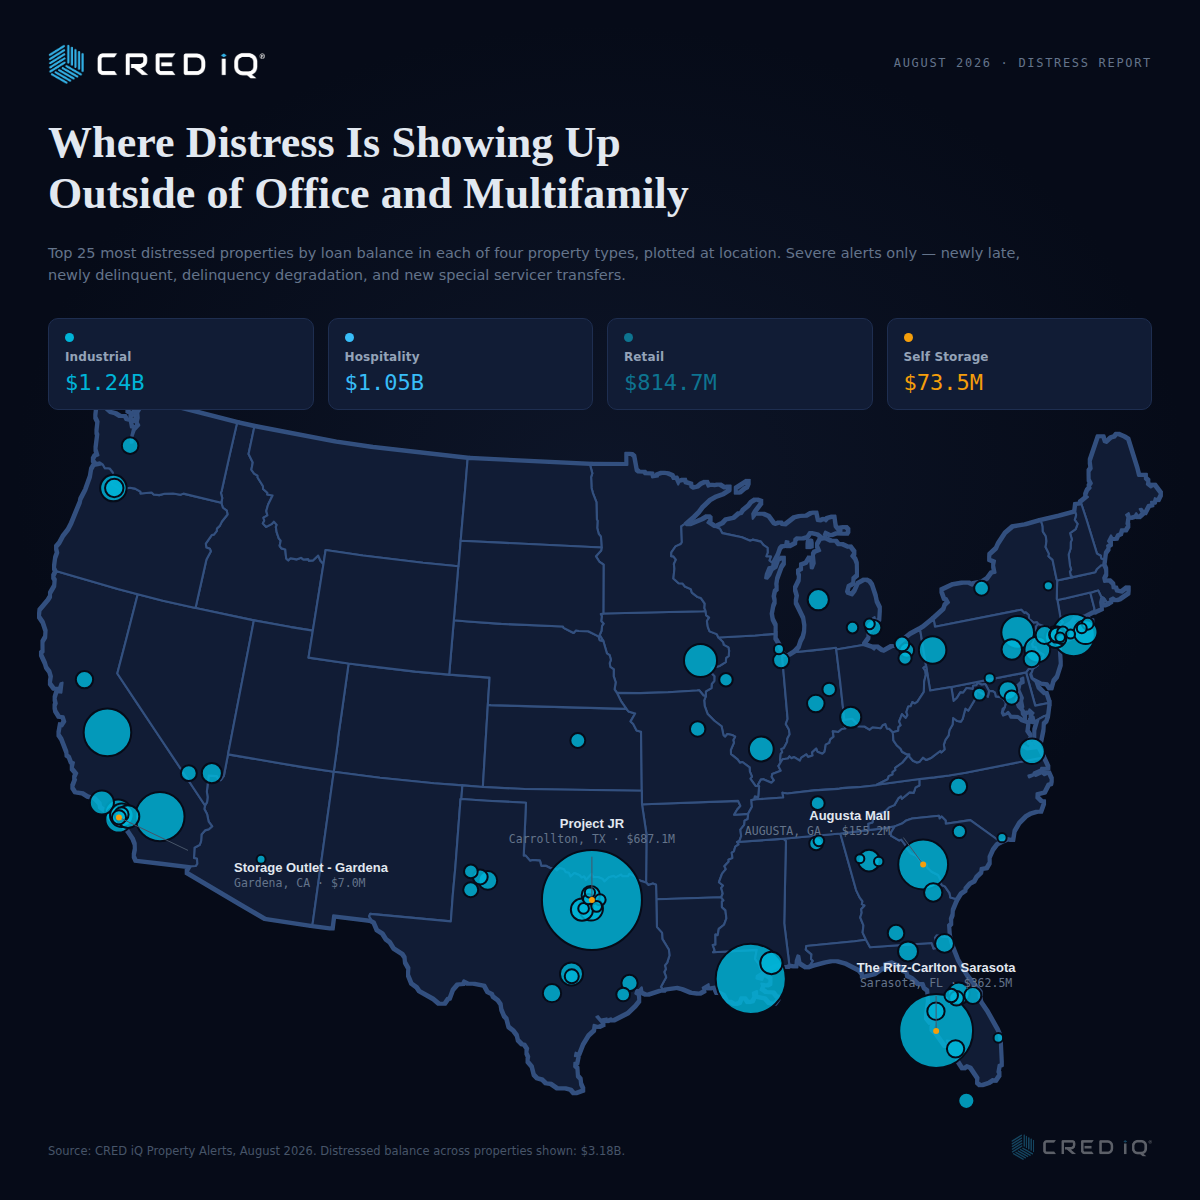
Industrial produced the single largest distressed loan in the entire report. Project JR, a warehouse and logistics property which has been converted to a data center in Carrollton, Texas, was originally structured with extension options and the borrower exercised the first of three options in June to push out its maturity. Midland, the servicer, nonetheless initially reported the loan as Performing Matured in early August; that status was later revised to Current. Across six pari passu notes (CONE 2024-DFW1), the loan totals $687.1 million. Industrial distress overall reached $1.41 billion across 101 severe alerts this month.
Hospitality distress centered on two large, name-brand assets. The Hyatt Regency New Orleans, a $325 million loan (NOHT 2019-HNLA), transferred to special servicing on a payment default — the largest new special servicer transfer of the month across any property type. The Ritz-Carlton Sarasota, a $362.5 million loan across four notes (BAMLL 2024-BHP), is now Newly Delinquent (Performing Matured) after missing its September maturity while continuing to pay. Hospitality distress overall reached $1.17 billion across 88 severe alerts this month.
Retail distress this month clustered in regional and outlet malls, coast to coast. Augusta Mall in Georgia, a combined $155.2 million across two notes, moved to Non-Performing Matured status on a balloon payment default. Fresno Fashion Fair Mall, $140 million combined across two notes, and Harlem USA in Manhattan, $108 million combined, both transferred to special servicing on imminent maturity default. Coral Ridge Mall in Iowa ($61.7 million) and The Shoppes at South Bay in Torrance, California ($37 million) both went newly late. Grove City Premium Outlets in Pennsylvania and Gulfport Outlet Mall in Mississippi, tied to the same MSC 2015-UBS8 deal, added $64 million combined. Retail distress overall reached $951.4 million across 89 severe alerts this month.
Self storage distress traced almost entirely to two national portfolio operators. A Prime Storage portfolio securitized in BMARK 2023-V4, $57.9 million across 91 properties spanning New York, Florida, Georgia, North Carolina, Connecticut, Arizona, Rhode Island, and Virginia, registered as newly late in the same cycle. A separate U-Haul portfolio in CD 2017-CD6, $23.6 million across 39 properties in more than a dozen states, did the same. Together the two portfolios account for the bulk of self storage’s $124 million in distressed balance this month, in a property type generally treated as close to recession-resistant.
Market Context
A limited refinancing environment combined with elevated interest rates continues to push loans past maturity across property types, not only the office and multifamily loans that typically dominate distress coverage.
Source: CRED iQ Property Alerts, August 2026. “Distress” includes Newly Late, Newly Delinquent (all maturity statuses), Delinquency Degradation (all stages), and New Special Servicer Transfer alert categories; excludes New Watchlist Loan additions.
