CRED iQ was happy to contribute data and analysis to last week’s insightful article in Commercial Observer by @AndrewCoen discussing the impacts of remote working on CMBS debt, and, in particular, loans secured by office properties. CRED iQ provided delinquency rates and special servicing rates for loans secured by office properties for primary markets across the U.S. Additionally, we offered guidance on identifying potential credit risks within the office sector as well as insights into the remote working dynamic. For those our followers that missed the story, below is a link to the article.
The COVID-19 pandemic has thus far not caused any material distress to CMBS office debt. Only 2.89 percent is in either delinquency or special servicing compared to 1.9 percent in 2019, according to data from commercial real estate data firm CRED iQ. Markets with the highest delinquency/special servicing rates including Hartford, Conn. (22.3 percent), St. Louis (19.2 percent), Houston (13.9 percent) and Indianapolis (13.62 percent).”
Marc McDevitt, senior managing director at CRED iQ, noted that delinquency and special servicing rates historically don’t provide guidance for future levels of distress. Lease rollover risk and market vacancy trends are instead better indicators of credit risks. McDevitt said many of the increased vacancies are tied to flight to quality with firms seeking office space with “higher wellness attributes” along with downsizing as companies reevaluate spacing needs amid the evolution of remote working habits.
“The office environment is a concern for CMBS investors in the long term as they monitor the rise in market vacancy rates, especially in [central business district] submarkets,” McDevitt said. “However, corresponding increases in delinquency will likely be delayed due to longer lease terms relative to retail. In the near-to-medium term, investors are likely concerned about pockets of lease rollover for certain assets in specific markets.
For full access to our loan database and valuation platform, sign up for a free trial below:
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. Our data platform is powered by over $2.0 trillion of CMBS, CRE CLO, SBLL, Ginnie Mae, FHA/HUD, and Agency loan and property data.
This week, CRED iQ examines the impact of commercial real estate values following a November 18, 2021 announcement by CVS Health regarding its strategic review of its retail business. New initiatives in the healthcare company’s omnichannel health strategy include the closures of 300 retail locations per year over the next 3 years. A total of approximately 900 store closures may be unwelcoming news to commercial real estate investors with CVS as primary tenant — property owners may face uncertain prospects for replacement tenants and the costs of backfilling a former CVS location.
For background, CVS listed a retail portfolio of approximately 80.1 million sf in its 2020 annual report, comprising 8,115 stores. CVS owns about 405 of those locations and leases the remainder as a tenant. Additionally, the company operates pharmacies for nearly 2,000 retail chains, including several grocers as well as Target via a 2015 agreement. Specific locations of stores closures have not yet been announced, but a reduction in store density will likely include overlapping operations in particular markets that may be deemed low growth. CVS locations with near-term lease expirations are candidates for closure, or renegotiations of rental rates; however, in the likely scenario where CVS closes stores prior to lease expiration, we expect the company would continue to honor its rent obligations.
CRED iQ leveraged its platform to identify properties leased to CVS as a single tenant or properties leased to CVS as one the 5 largest tenants by GLA on the property’s rent roll. CRED iQ’s subset of nearly 400 properties with CVS as a Top 5 tenant secures approximately $4 billion in outstanding commercial real estate debt. More than half of the properties, accounting for only 19% of the aggregate securitized debt, are single tenant or net lease properties. Classifying properties by lease expiration date, CRED iQ was further able to isolate properties with CVS lease expirations over the next 3 years as shown in the table below:
Lease Expiration Year
# of Properties
Aggregate Outstanding Balance ($000’s)
2021 or Earlier
11
$291,532
2022
14
$163,782
2023
27
$327,592
2024
24
$341,789
For a copy of the comprehensive list of all CMBS properties with CVS as a Top 5 tenant — including over 200 single tenant locations, please reach out to Shane Beeson (shane@cred-iq.com) or click the link below.
This week’s WAR Report focuses specifically on net lease properties, a property sub-type of retail where the credit quality of a commercial real estate mortgage is often tied to the credit quality of the single tenant’s corporate entity. CVS is a popular tenant among net lease investors because pharmacies qualify as an essential retail use and locations are often centrally located to primary corridors of commerce such as signalized intersections and desirable corner lots. Absent a credit tenant, a property’s location, age, and quality become pertinent factors in evaluating valuation scenarios. Featured properties below include single tenant CVS retail locations with near-term lease expirations or CVS locations that secure loans in special servicing.
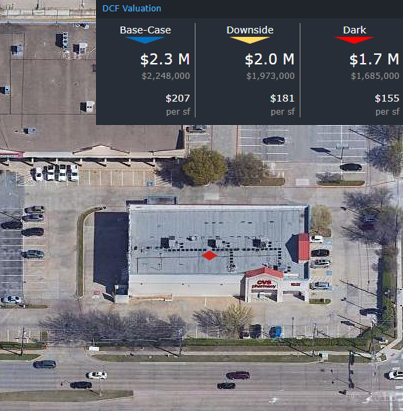
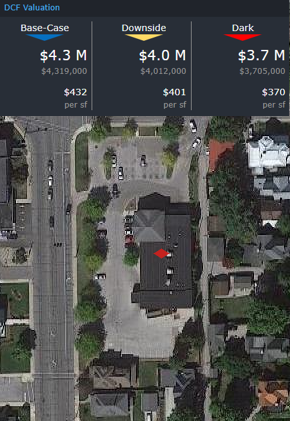
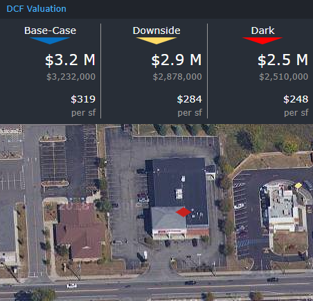
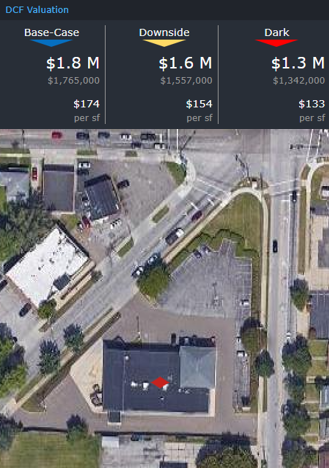
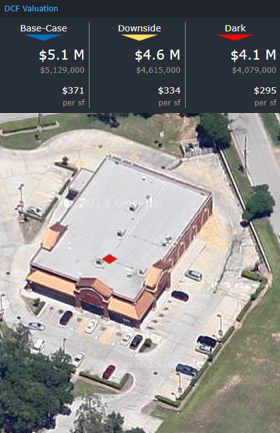
The CRED iQ valuations factor in a base-case (expected lease renewal at in-place rent), a downside (lease renewal at 50% reduction in rent), and dark scenarios (100% vacant). Select valuations are provided for the properties below. For full access to the valuation reports including all 3 valuation scenarios as well as full CMBS loan reporting, with detailed financials, updated tenant information, and borrower contact information, sign up for a free trial here.
Solomon CVS Portfolio
37,431 sf, Single Tenant Retail, Texas and Mississippi[View Details]
This $6.8 million loan is secured by a portfolio of 3 single tenant CVS Pharmacy retail stores. Two of the properties are located outside of Dallas, TX and the third property is located outside of Jackson, MS. The CVS location at 1501 Independence Parkway in Plano, TX had a lease expiration on October 26, 2021. CVS was still operational at the location into November; however, store density may be a concern with another CVS located less than 2 miles away. Both stores are well-positioned on corner lots but the competitive CVS benefits from Aldi as a grocery anchor whereas the subject CVS has less compelling demand generators. Other competition in the area includes several Walgreens locations and pharmacies operated by Walmart, Kroger, and Tom Thumb. The property was constructed in 1996 and does not appear to have been renovated.
The CVS in Brandon, MS has a lease expiration in August 2023 and the CVS in Paris, TX has a lease expiration in April 2024. Both locations are strategically located at intersections with minimal cannibalization from proximate CVS locations. Loan maturity is slated for September 6, 2025. For the full valuation report and loan-level details for the CVS Plano property, click here.
10,000 sf, Single Tenant Retail, Goshen, IN[View Details]
This $3.0 million loan transferred to special servicing on February 26, 2020 due to delinquency and an unresponsive borrower. The loan was originated in March 2018 but the borrower has not reported updated financial statements since origination. CVS pays $25/sf at the freestanding building with a lease that expires in January 2038. The borrower estimated sales at the property to be approximately $1,350 per square foot. However, local residents have noted the pharmacy’s inability to stay open regularly throughout the pandemic amid staff shortages. Also notable, there is a Target, which contains a CVS Pharmacy, located 5 miles away that may be the more preferable option in terms of convenience, reliability, and amenities. The property has been listed for sale for $5 million, equal to $500/sf. The long-term lease is a positive factor; however, this particular location may be at risk of having a dark tenant. The property was constructed in 2000. For the full valuation report and loan-level details, click here.
10,125 sf, Single Tenant Retail, Johnson City, NY[View Details]
This 10,125-sf freestanding CVS Pharmacy, located in Johnson City, NY, is part of a 2-property portfolio that serves as collateral for a $3.8 million loan. The property’s lease with CVS expires on January 31, 2024, which is within the company’s 3-year timeframe for closures. The building, which was constructed in 1998, is one of the oldest single tenant CVS locations within CRED iQ’s database. The property’s location is on a main thoroughfare but is inferior to a neighboring Walgreens, which has a dedicated turning lane and a three-way junction. This particular CVS location on Main Street also competes with another CVS Pharmacy, located less than a mile away; although the Main Street pharmacy is more proximate to a UHS medical center, which is part of the region’s primary healthcare system, and several medical offices. Loan maturity is scheduled for August 6, 2025. For the full valuation report and loan-level details, click here.
This $1.5 million loan is secured by a 10,125-sf freestanding CVS Pharmacy in Akron, OH. The loan was added to the servicer’s watchlist in August 2019 with commentary stating that CVS vacated at lease expiration in January 2020; however, additional servicer data offers a contradictory lease expiration date of January 31, 2025, which is in the final year of announced store closures. CRED iQ confirmed the 780 Brittain Road location was operational shortly following the closure announcement; however financial statements for year end 2020 indicate base rent was reduced by approximately 32% compared to the prior year. The property shares a signalized intersection with Walgreens. A superior CVS with more flexible store hours is located only 1.5 miles away in an Acme-anchored shopping center. The property was constructed in 1999. For the full valuation report and loan-level details, click here.
13,824 sf, Single Tenant Retail, Conroe, TX[View Details]
This $364,000 loan is secured by a CVS Pharmacy in Conroe, TX, located approximately 40 miles north of Houston. CVS has a lease expiration in October 2022. The near-term lease expiration suggests the Conroe location is a candidate for closure. The property competes with 3 Walgreens stores within a 5 miles radius but there are no other CVS locations in the area. One option for CVS is to open a Pharmacy or MinuteClinic in a neighboring Target, which was last remodeled in 2018. The Conroe location was constructed in 2002. For the full valuation report and loan-level details, click here.
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. Our data platform is powered by over $2.0 trillion of CMBS, CRE CLO, SBLL, Ginnie Mae, FHA/HUD, and Agency loan and property data.
The CRE Data, Analytics, and Valuation platform has entered the Operating Advisor business within the CMBS Industry
RADNOR, Pa. – CRED iQ, a data, analytics and valuation platform serving the commercial real estate finance and investment communities announced its expansion into the Operating Advisory business for Commercial Mortgage-Backed Securities (CMBS). The Operating Advisor role was introduced to the industry post financial crisis to review Asset Status Reports for defaulted loans, evaluate proposals by the special servicer in handling defaults, and recalculate appraisal reduction amounts. Additional responsibilities are triggered once a Control Termination Event occurs within a transaction.
As part of its newly expanded role, CRED iQ made critical hires of industry veterans, Jim Reed and Marc McDevitt. Jim Reed has over 15 years of asset management and workout experience with Oppenheimer and Capmark. Marc McDevitt was a senior member of Kroll Bond Rating Agency (KBRA) where he led a team of analysts tasked with identifying, monitoring and valuing distressed commercial properties.
CRED iQ Co-Founder Bill Petersen explains “Moving into the Operating Advisor role was a natural progression for the platform since we are already monitoring and valuing distressed assets across the CMBS universe. We often identify loans at risk of default long before they become delinquent or transfer to the special.” Prior to Co-founding CRED iQ, Petersen ran the CMBS Ratings Surveillance group for Kroll Bond Rating Agency. “We have decades of experience with identifying, monitoring, and valuing risky assets, as well as a deep understanding of CMBS structures and processes. We look forward to drawing upon our experience to inform our discussions with the servicers.”
“We are thrilled to have Jim and Marc join CRED iQ and help us expand into a new business line that serves the CMBS industry”, said CRED iQ Co-Founder, Michael Haas.
CRED iQ is a commercial real estate data, analytics and valuation platform serving professionals across the CRE investment, brokerage, and lending industries. Updated monthly, CRED iQ’s robust database is powered by over $2.0 trillion of loan and property data from the securitized universe. CRED iQ tracks data on CMBS Conduit, SBLL, CRE CLO, and Agency debt combined with verified borrower and true ownership contact details.
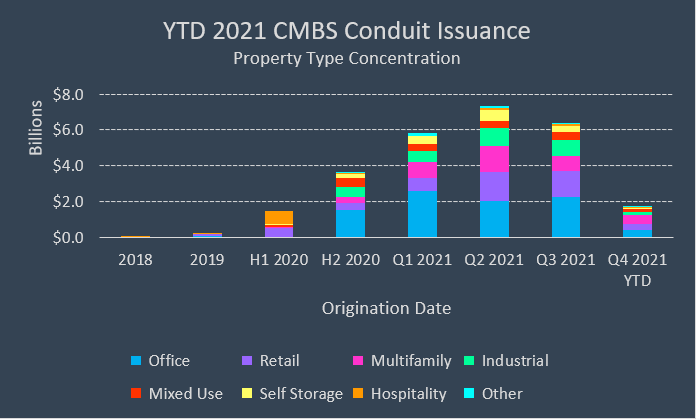
CMBS conduit issuance through mid-November 2021 totaled approximately $26.4 billion as the market gears up for a final push to close out the year. Parsing out issuance and origination trends for loans securitized in 2021 conduit deals provides insight into the commercial real estate lending landscape across all major property types.
Evaluating YTD 2021 conduit issuance by property type concentration reveals a heavy preference for office collateral, which made up 33% of total securitized conduit debt. Office was followed by retail, multifamily, industrial, and mixed-use, respectively, in conduit issuance through mid-November 2021. Hotel collateral significantly lagged these property types based on pandemic-related concerns. Retail may come as a surprise for its showing as second-overall in issuance with $5.3 billion; however, long gone are frequent originations of massive debt packages secured by super-regional malls. Instead, retail originations now comprise more net lease portfolios and grocery-anchored centers. There are two malls securing notes that were securitized in 2021; however, both loans — Kings Plaza and The Westchester — were originated in December 2019 and January 2020, respectively. Retail loans were generally seasoned for twice as long as office loans before being securitized. About 20% of the retail loans securitized in 2021 conduit deals were originated in 2019 or 2020, indicating investors’ higher perception of credit risk associated with the collateral.
Seasoning has become more common for the 2021 vintage with lenders holding on to loans comparatively longer than in the past. Approximately 20% of CMBS conduit loans securitized this year were originated prior to 2021. Seasoning was especially noticeable for loans secured by lodging properties with 78% of originations occurring prior to July 1, 2020. The most severe example was a $6.3 million loan that was originated in October 2018, secured by a hotel located in NJ, within the Philadelphia, PA MSA. After two modifications and, presumably, improved collateral performance since the onset of the pandemic, the loan was sold to a CMBS securitization. On average, hospitality loans were seasoned 9 months before securitization, which was by far the longest among all property types. Self-Storage and Industrial loans were the quickest between origination and securitization with an average just under one month.
Exploring loan and property metrics a bit further for 2021 CMBS conduit issuance again puts the spotlight on lodging loans. CRED iQ examined four primary loan and property metrics for each major property type and found that hospitality loans, on average, were structured the most conservatively. Interest rates for lodging loans were the second highest at a weighted average of 3.79%, trailing only manufactured housing loans. Hotel loans had the lowest LTVs among 2021 issuance, which may be derived from several factors, including value depreciation since April 2020, stricter underwriting requirements by originators, and lenders’ overall wariness of the risks associated with a property type that was hit hardest by the pandemic. Lenders’ risk appetite for hotel loans is further evidenced by weighted average debt yield metrics. Loans secured by lodging assets had a debt yield of 15.86%, which was at least 500 basis points greater than the next highest property type, office, with a 10.69% weighted average debt yield.
Loan and Property Metrics for 2021 YTD CMBS Conduit Issuance
WA Interest Rate
WA LTV
WA Debt Yield (UW NCF)
WA Implied Cap Rate (UW NCF)
Office
3.30%
54.47%
10.69%
4.29%
Retail
3.61%
57.63%
10.55%
5.38%
Multifamily1
3.70%
60.99%
8.53%
4.54%
Industrial
3.51%
57.40%
10.08%
4.31%
Mixed Use1
3.42%
56.77%
9.48%
3.98%
Self Storage
3.58%
59.29%
9.83%
4.92%
Hospitality
3.79%
49.02%
15.86%
7.10%
Other
3.43%
49.86%
8.42%
4.03%
Manufactured Housing
4.09%
57.56%
9.78%
4.60%
1 Excludes Cooperatives * Through November 17, 2021
Using appraisal values from origination and the originators’ underwritten net cash flow, CRED iQ calculated implied capitalization rates for each sector and the results were consistent with previously examined loan metrics. The weighted average cap rate for lodging collateral was 7.10%, which was considerably higher than the next highest, retail, at 5.38%. Mixed-use properties had the lowest weighted average cap rate at 3.98%. Much of the mixed-use collateral consisted of properties with a multifamily component located in a gateway or primary market, contributing to comparatively lower cap rates. Additionally, industrial and office collateral had relatively low cap rates compared to most property types, averaging about 4.30%. With year-end 2021 quickly approaching, we don’t expect to see meaningful variation from the highlighted metrics in newly securitized conduit loans; although, collateral mix and originators’ comfort levels with hospitality will continue to be closely monitored.
About CRED iQ
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. Our data platform is powered by over $2.0 trillion of CMBS, CRE CLO, SBLL, Ginnie Mae, FHA/HUD, and Agency loan and property data.
Freddie Mac loans secured by distressed properties are sources for opportunities within the multifamily sector that include traditional garden-style and high-rise as well as multiple property sub-types, including student housing and senior housing properties that were among those highlighted this week. Mortgage originators, distressed investors, and commercial brokers are able to search CRED iQ’s database of approximately 26,000 Freddie Mac loans totaling $336 billion in outstanding debt for their next opportunity. The properties featured in this week’s WAR Report secure a subset of distressed Freddie Mac loans across multiple primary markets, including Philadelphia, San Diego, San Antonio, and Los Angeles. This week, CRED iQ calculated real-time valuations for 5 distressed multifamily properties that secure Freddie Mac loans. Click the link below for a list of all multifamily properties.
CRED iQ valuations factor in base-case (Most Likely), downside (significant loss of tenants), and dark scenarios (100% vacant). For full access to the valuation reports as well as full CMBS loan reporting, including detailed financials, updated tenant information, and borrower contact information, sign up for a free trial here.
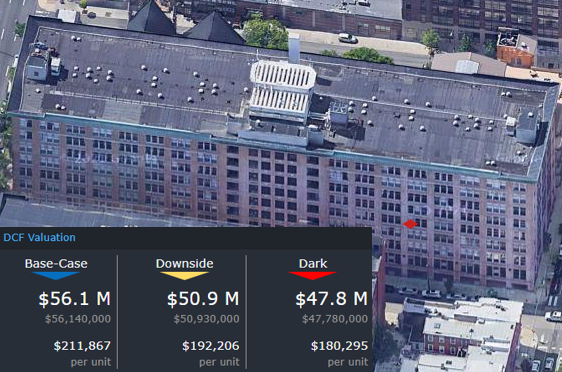
This $40.1 million loan transferred to special servicing on October 28, 2020 and has been over 90 days delinquent since. CWCapital, as special servicer, has filed for receivership multiple times but the motions were denied. A short-term forbearance agreement was initially agreed upon in April 2021 at the onset of the pandemic but the property’s poor performance can be traced back to pre-pandemic operational struggles. For this reason, the borrower’s request for an extension of forbearance after the initial 3-month period was denied. Workout of the loan is ongoing and the special servicer appears to be continuing with its strategy of foreclosure.
The mortgage is secured by a 9-story, 265-unit loft-style multifamily property in the Fairmount submarket of Philadelphia. Occupancy at the property started to show declines in 2016 when it dropped to 91 from 96%. Occupancy then continued to decline below 90% in the following years and was as low as 75% during the pandemic before recovering to 97% as of September 2021. Additionally, the property benefitted from a 10-year real estate tax abatement from the City of Philadelphia that expired at year-end 2016. In 2017, unabated real estate taxes increased nearly 5x to approximately $769,000. By the end of 2019, net cash flow from the property was not sufficient to cover the loan’s debt service.
The property appraised for $53.9 million ($203,396/unit) in February 2021, which represented a 14% decline in value compared to the property’s 2011 appraisal. For the full valuation report and loan-level details, click here.
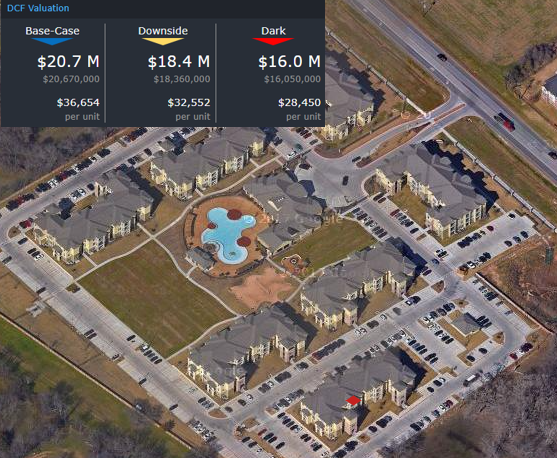
This $24.6 million loan transferred to special servicing on February 3, 2021 after failing to stay current following the end of a forbearance period. An initial forbearance agreement was granted in September 2020 to provide COVID relief and the payback period was scheduled to begin in December 2020; however, the tenants-in-common borrowing entity did not make any repayments. The loan became severely delinquent for several months after it transferred to special servicing. CWCapital, as special servicer, reached an agreement with the borrower to cure the loan and a second forbearance agreement was signed in September 2021. The loan has been current in payment in accordance with the terms of the forbearance since the second agreement was executed. The window for clearing up credit issues for this loan is getting shorter with loan maturity scheduled for January 2023.
The loan is secured by a 186-unit student housing facility located in Waco, TX. The property contains 564 beds and provides housing to students enrolled at Baylor University, which is located about 1.5 miles away. Despite receiving COVID-related forbearance, the property has had occupancy issues prior to the pandemic and was 70% occupied in 2019. Newer housing options and locations closer to campus were reasons cited for low occupancy. Occupancy appears to have recovered for the 2021 academic year and was most recently reported as 97% as of October 2021. The property was appraised for $23.2 million ($41,135/bed) in February 2021, which represented a 34% decline in value compared to the property’s August 2015 appraisal at origination. For the full valuation report and loan-level details, click here.
60 units, Assisted Living Facility, San Diego, CA[View Details]
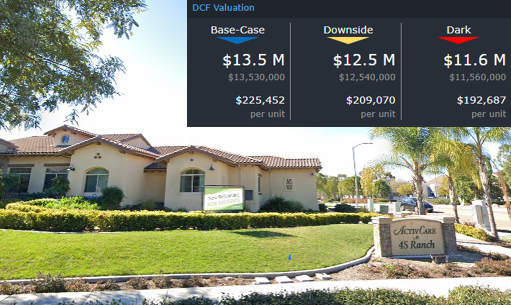
This $9.8 million loan has had delinquency issues since July 2021 and was most recently over 90 days delinquent in November. The loan is secured by a 60-unit senior living facility in San Diego, CA that provides memory care and specialized assisted living accommodations. The loan first became delinquent after a 3-month forbearance period ended in May 2021. A second forbearance period was agreed upon by the servicer and the relief period appears to have been extended. Occupancy at the property was 37% as of July 2021, which is a reflection of the severe impact from the pandemic. However, the borrower has stated plans to partner with local non-profits to provide residential housing to those in need of assisted living care. Contract revenue from such a partnership may aid in the property’s stabilization as forbearance is repaid over the next 24 months. For the full valuation report and loan-level details, click here.
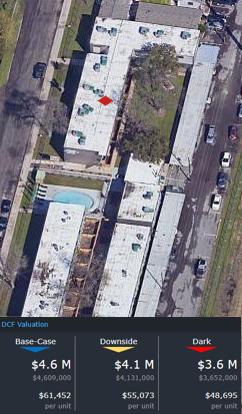
This 75-unit multifamily property in northeast San Antonio, TX is facing foreclosure due to payment default on a $4.9 million mortgage. The loan transferred to special servicing in August 2021 and the foreclosure sale is scheduled for December 2021. A 3-month forbearance agreement for the loan had been signed in March 2021 but the borrower was unable to keep up with repayments starting in June 2021. Occupancy at the property was impacted by the pandemic and declined to as low as 72% during 2020 before recovering to 91% as of June 2021. For the full valuation report and loan-level details, click here.
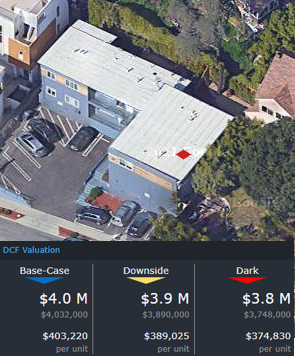
This $2.6 million loan transferred to special servicing on November 4, 2021 due to delinquency. The loan is secured by a 10-unit multifamily building in the Echo Park neighborhood of central Los Angeles. The 2-story property is built into a hillside and is located just off Sunset Boulevard, in close proximity to Dodgers Stadium. The mortgage, which was 60 days delinquent as of November, is still in the early stages of workout. The property was 100% occupied as of year-end 2020; however, updated occupancy and performance figures were not yet reported for 2021. For the full valuation report and loan-level details, click here.
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. Our data platform is powered by over $2.0 trillion of CMBS, CRE CLO, SBLL, Ginnie Mae, FHA/HUD, and Agency loan and property data.
CRED iQ monitors distressed rates (DQ + SS%) and market performance for nearly 400 MSAs across the United States, covering over $900 billion in outstanding CRE debt. Distressed rates for the current month and month-over-month changes are presented below, by property type, for the 50 largest markets. The lodging sector continues to be the most volatile, accounting for four of the 10 largest percentage increases in distress by market-sector and five of the 10 biggest percentage decreases in distress by market-sector.
The retail market in Nashville exhibited the highest increase in distress this month, which was caused by the transfer of a $155 million mortgage secured by regional mall CoolSprings Galleria to special servicing. The loan transferred to special servicer due to the bankruptcy of the loan sponsor, CBL Properties. Another notable market sector was Chicago office, which saw its distress rate increase 3.6% to 9.2%. The increase in Chicago office distress was primarily driven by 175 West Jackson, which secures a $280 million mortgage that recently transferred to special servicing.
The Austin hotel market exhibited the greatest month-over-month improvement following a positive development with one of the city’s most prominent hotels. The Fairmont Austin, which secures a $300 million mortgage, returned to the master servicer following a modification.
The Top 5 distressed markets remained unchanged from the prior month. The Minneapolis MSA has the highest overall distressed rate at 23.7%. Louisville (21.1%), New Orleans (14.8%), Cleveland (12.1%), and Milwaukee (10.7%) round out the list of markets with the highest rates of distress. The Allentown and Sacramento MSAs have the lowest percentage of distress among the Top 50 with rates less than 1%.
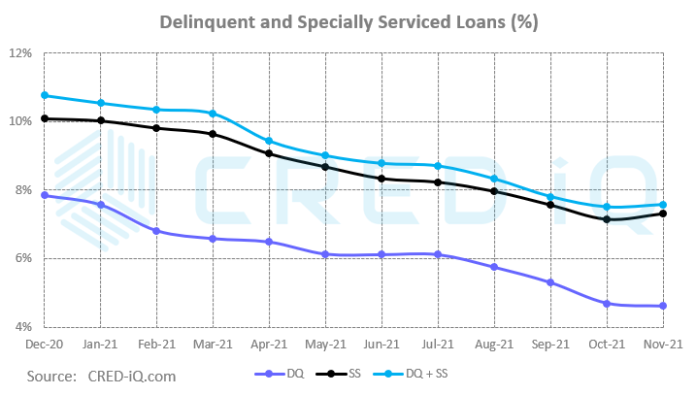
The CRED iQ overall delinquency rate declined this month and extended its streak of consecutive improvements to 17 months. The delinquency rate, equal to the percentage of all delinquent specially serviced loans and delinquent non-specially serviced loans, for CRED iQ’s sample universe of $500+ billion in CMBS conduit and single-asset single-borrower (SASB) loans was 4.62%, down from 4.70% last month. Conversely, CRED iQ’s special servicing rate, equal to the percentage of CMBS loans that have transferred to special servicing, increased month-over-month to 7.32% from 7.15% previously. The increase in the special servicing rate was the first in nearly 15 months and was mainly driven by the recent transfers of a $1.2 billion mortgage secured by the 245 Park Avenue office building in Manhattan, NY and a $280 million loan secured by the 175 West Jackson office property in Chicago, IL. Aggregating the two indicators of distress – delinquency rate and special servicing rate – into an overall distressed rate (DQ + SS%) equals 7.58% of CMBS loans that are specially serviced, delinquent, or a combination of both, which is an increase compared to 7.51% in the prior month.
DQ = All delinquent CMBS loans in the conduit and SASB universe, including specially serviced and non-specially serviced loans SS = All specially serviced CMBS loans in the conduit and SASB universe, including current, delinquent and REO DQ + SS = All distressed CMBS loans in the conduit and SASB universe that are delinquent, specially serviced, or a combination of both
By property type, individual delinquency rates for lodging and retail exhibited modest month-over-month improvements but still remain the two most distressed sectors. The delinquency rate for multifamily increased compared to last month but remains in line with its trailing 12-month average of 2.3%. The delinquency rate for office remained flat, but the special servicing rate for office collateral notably spiked. This month’s transfers of 245 Park Avenue and 175 West Jackson contributed in pushing the office special servicing rate to its highest level in a year to 3.26%. With the increase, the office special servicing rate surpassed multifamily to become third-highest among property types.
DQ = All delinquent CMBS loans in the conduit and SASB universe, including specially serviced and non-specially serviced loans SS = All specially serviced CMBS loans in the conduit and SASB universe, including current, delinquent and REO DQ + SS = All distressed CMBS loans in the conduit and SASB universe that are delinquent, specially serviced, or a combination of both
CRED iQ also monitors an overall distressed rate (DQ + SS%) by property type to account for loans that qualify for either delinquent or special servicing subsets. The overall distressed rates typically track slightly higher than special servicing rates as most delinquent loans are also with the special servicer. This month, overall distressed rates for lodging, retail and self-storage declined while office, multifamily, and industrial increased. The increase in the overall distressed rate for office to 3.48% was most noteworthy and was weighted by an increase in the office special servicing rate. Although 245 Park Avenue and 175 West Jackson transferred to special servicing, both loans remained current in payment. For additional information for these two loans including updated leasing information for 245 Park Avenue, click View Details below:
This week, CRED iQ calculated real-time valuations for 5 office and industrial properties that have major tenants with lease expirations in the next 6 months. Featured leases include tenant spaces at industrial/flex complexes in Houston, TX and Los Angeles, CA as well as large blocks of office space in the Phoenix, Portland, and Minneapolis MSAs. Lease expirations are opportunities for tenant reps to source options and find solutions for clients. Additionally, lease expirations can serve as a preemptive signal of distress for CRE loans if prospects for leasing the newly vacant space are low.
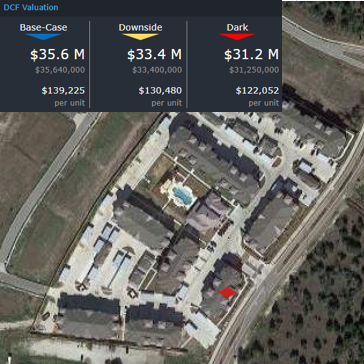
The CRED iQ valuations factor in a base-case (Most Likely), a downside (significant loss of tenants), and dark scenarios (100% vacant). Select valuations are provided for the properties below. For full access to the valuation reports including all 3 valuation scenarios as well as full CMBS loan reporting, with detailed financials, updated tenant information, and borrower contact information, sign up for a free trial here.
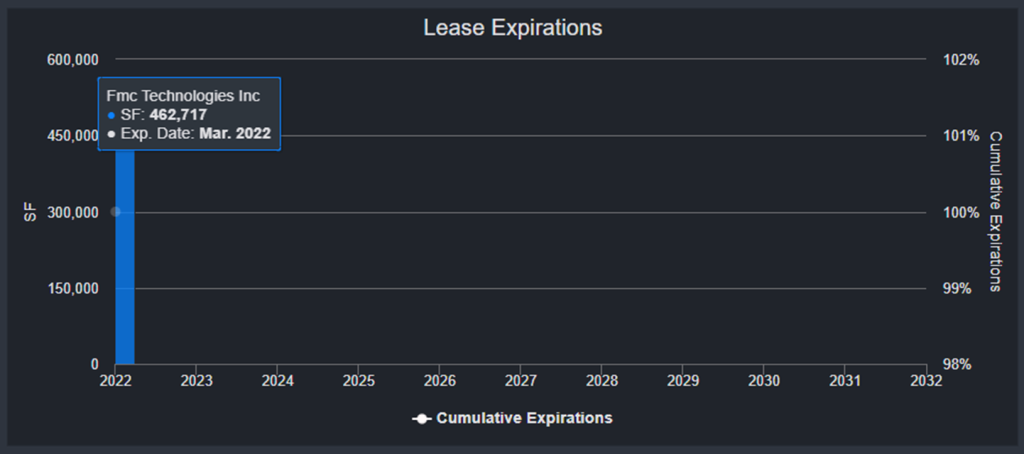
TechnipFMC leases approximately 462,000 sf of industrial space in the North Belt submarket of Houston, TX. Although the lease expires on March 31, 2022, TechnipFMC physically vacated the property in 2017 after a merger between FMC Technologies and Technip SA created the need to consolidate operations. As first reported by the Houston Business Journal, brokerage firms Binswanger and Avison Young were retained to sublease the remaining term of TechnipFMC’s lease following the merger. The property secures a $27.2 million mortgage with a maturity date in 2037. The loan had an anticipated repayment date (ARD) in 2017 but refinancing at the time was likely difficult with a dark property. The industrial complex spans 38 acres and allows for heavy manufacturing uses with several dock high doors and cranes. Unlike Houston’s office market, which has had its struggles with large blocks of empty space, the industrial market has seen declining vacancy rates in 2021, which offers an optimistic view on the leasing prospects for the property. However, there has not been a replacement tenant for more than 3 years. For the full valuation report and loan-level details, click here.
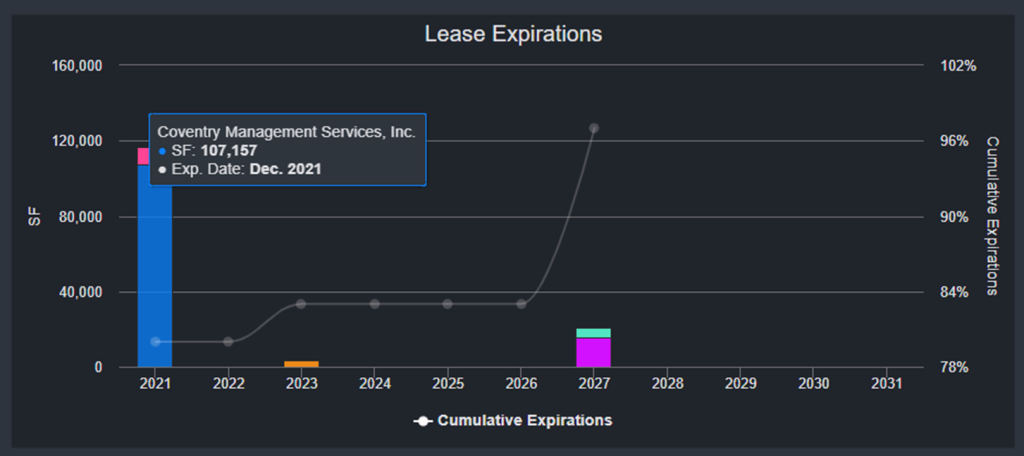
Aetna is vacating approximately 107,000 sf of office space in the Old Town neighborhood of Scottsdale, AZ upon its December 31, 2021 lease expiration. The property, a 3-story office building, secures a $25.2 million mortgage that is scheduled to mature on February 6, 2025. Aetna accounts for about 73% of the property’s GLA. The healthcare company used the space for its Coventry Health Care operations, which it acquired in 2012. CRED iQ estimates occupancy of 24% for the office building following the departure of Aetna. Prior to loan origination in 2015, the property operated with 71% occupancy for several years. The office building benefits from a central downtown location, however, several adjacent office buildings also have substantially large blocks of office space available, including the Scottsdale Financial Center. For the full valuation report and loan-level details, click here.
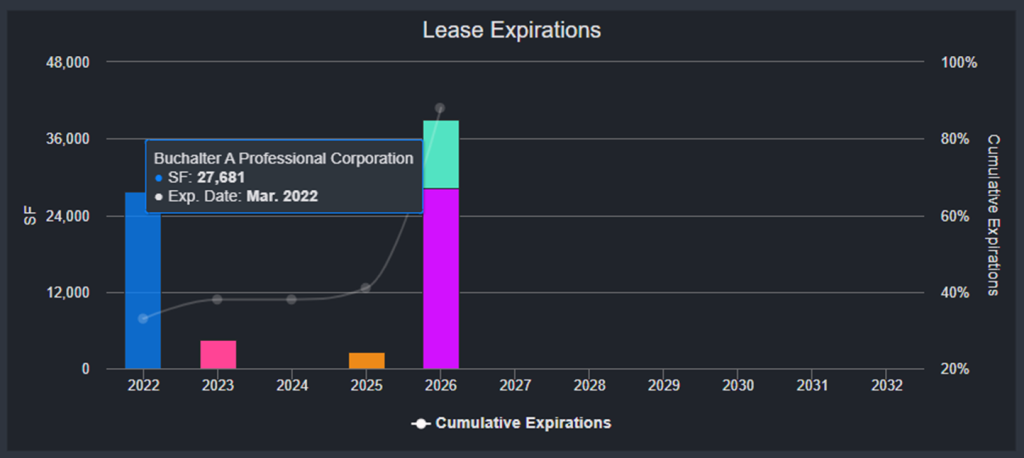
Buchalter is vacating 27,681 sf of space at lease expiration on March 31, 2022 at the Lovejoy office property in the Pearl District neighborhood of Portland, OR. The Oregon-based law firm is moving to Fox Tower, a 27-story Class-A building located more centrally to Portland’s CBD. Buchalter’s lease accounted for 33% of the GLA at the property, which secures a $24.0 million mortgage. The property’s largest tenant, Ruby Receptionists, has a lease that accounts for 34% of the GLA and expires in 2026. CRED iQ estimates occupancy will be approximately 57% following the departure of Buchalter. The mortgage is scheduled to mature on July 11, 2024. For the full valuation report and loan-level details, click here.
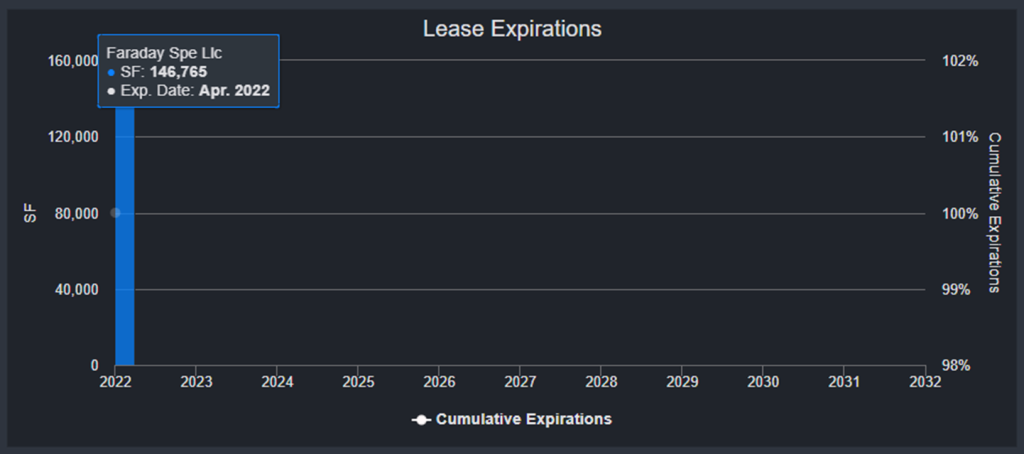
Faraday Future, an electric vehicle manufacturer, is the sole tenant at a flex industrial property located approximately 14 miles south of downtown Los Angeles. Its lease agreement has an initial expiration of April 30, 2022 with two, 5-year extension options. The tenant previously owned the property, which consists of two buildings containing creative office space and R&D facilities, but sold it to Atlas Capital Group in a sale-leaseback transaction that closed in March 2019. The property still serves as Faraday Future’s headquarters. Although the tenant has given no indication of its intent to extend or vacate, a positive signal for a lease renewal occurred in July 2021 when the EV manufacturer became a publicly traded company. Prior to this, concerns about the company’s financial viability were well publicized, including a failed venture with foreign real estate firm Evergrande. Should Faraday vacate, the borrower plans to market the available space as flex or reposition the property as creative office pending availability of capital. CRED iQ calculated a dark value for the property in the scenario that Faraday Future vacates. For the full valuation report and loan-level details, click here.
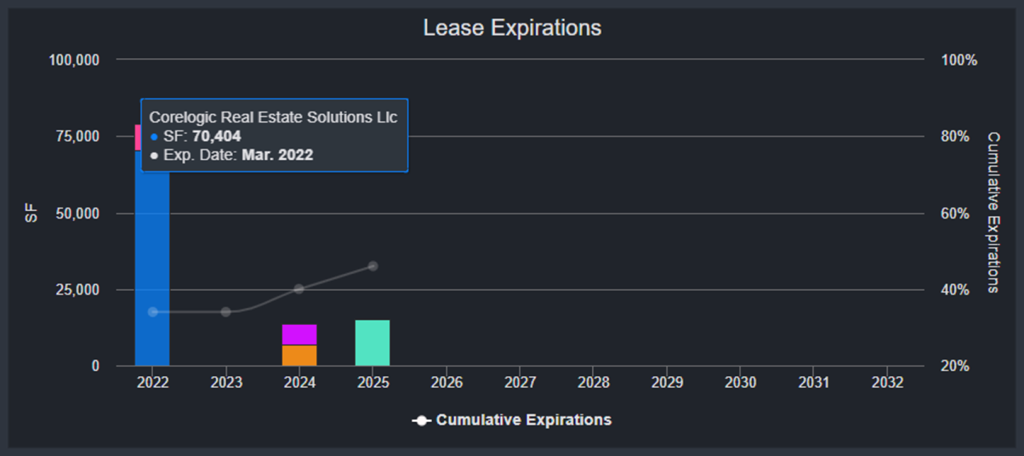
CoreLogic has a 70,404-sf lease expiring on March 31, 2022 at a suburban office building located 10 miles south of Minneapolis, MN. The tenant closed its offices at the building in 2019 and the space has since been dark. CoreLogic was the largest tenant at the property and accounted for 30% of the GLA. Riverview Office Tower is a 15-story Class-B tower located just south of the Minneapolis – Saint Paul International Airport in close proximity to the Mall of America. Occupancy for the property has been consistently low and was most recently reported to be 68% as of June 2021. CRED iQ anticipates economic occupancy declining to 38% following the expiration of CoreLogic’s lease. For the full valuation report and loan-level details, click here.
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. For full access to our loan database and valuation platform, sign up for a free trial below:
This week, CRED iQ calculated real-time valuations for 5 distressed multifamily properties that secure GNMA loans. Ginnie Mae loans secured by distressed properties as well as loans with near-term maturities are sources for intriguing opportunities within the multifamily sector that expand into several property sub-types, including affordable housing and student housing. Mortgage originators, distressed investors, and commercial brokers are able to search CRED iQ’s database of approximately 15,000 Ginnie Mae loans totaling more than $138 billion in outstanding debt for their next opportunity. The properties featured in this week’s WAR Report secure a subset of the largest distressed Ginnie Mae loans by outstanding balance that are at least 60 days delinquent.
CRED iQ valuations factor in a base-case (Most Likely), a downside (significant loss of tenants), and dark scenarios (100% vacant). For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including detailed financials and borrower contact information, sign up for a free trial here.
Residence at Oakmont
256 units, Multifamily, Bryan, TX
GNMA 2020-36197DLG1
This $28.8 million loan, which is over 120 days delinquent, is secured by a 3-story, 256-unit multifamily property in Bryan, TX, located about 100 miles northeast of Austin, TX. The loan was over 90 days delinquent in the prior reporting period. The mortgage was issued through the Department of Housing and Urban Development’s (HUD) 221(d)(4) program to facilitate the construction and rehabilitation of multifamily properties for low to moderate-income families. Orix Real Estate Capital originated the mortgage in June 2017 and construction of the property began soon after. The loan has a 3.83% interest rate, a maturity date in April 2059, and a 10% prepayment penalty that declines annually by 100 basis points through the first 10 years its term. For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including borrower contact information, sign up for a free trial here.
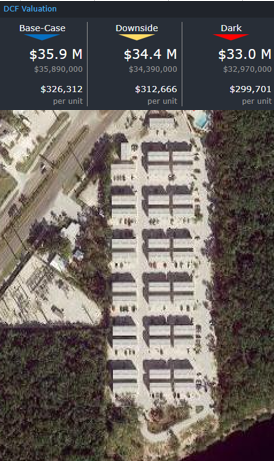
This $21.2 million loan, which is 6 months delinquent, is secured by a 2-story, 110-unit multifamily property located in Key Largo, FL. Similar to the Residence at Oakmont, this mortgage was issued through HUD’s 221(d)(4) program to facilitate the construction of multifamily properties for moderate-income families. Wells Fargo Multifamily Capital originated the loan in 2011 just prior to development and construction of the collateral property. The loan, which has an interest rate of 3.62%, is scheduled to exit its prepayment penalty period in January 2022. Maturity is scheduled for August 2052. CRED iQ’s data records indicate the loan was modified, although details regarding the terms of the modification were not provided by the servicer. Despite the distressed nature of the loan, the collateral likely benefits from limited multifamily inventory in the Key Largo market as well as barriers to entry with regards to new development. For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including borrower contact information, sign up for a free trial here.
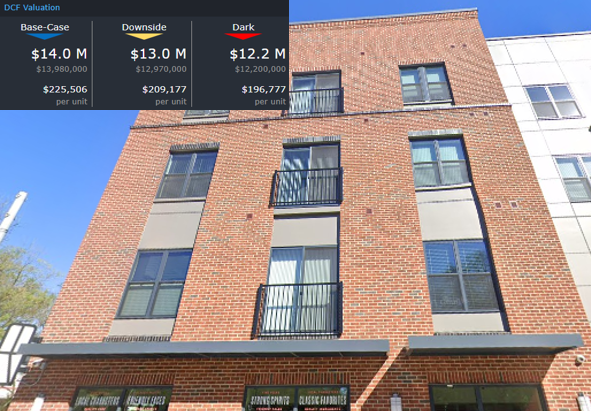
This $11.6 million loan, which is over 90 days delinquent, is secured by a 62-unit mixed-income apartment complex located in the Bolton Hill neighborhood of Baltimore, MD. The loan was originated by Wells Fargo Multifamily Capital under Section 221(d)(4) in February 2018 through the Choice Neighborhood Program, which operates under the HUD. The loan has a 3.75% interest rate and a 10% prepayment penalty that declines 1% annually. Loan maturity is scheduled for August 2059.
Prior to construction in 2018, the property served as a parking lot for the Linden Park Apartments, a 266-unit senior-living facility that serves as collateral for a $13.6 million GNMA mortgage loan. The Jordan Apartments became open for leasing in 2019 and offers mixed-income rental rates. The property features a ground-floor restaurant and benefits from a 10-year property tax credit from the city of Baltimore based on the property’s National Green Building Standard Certification. CRED iQ’s Base-Case valuation uses estimates for fully unabated property taxes. For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including borrower contact information, sign up for a free trial here.
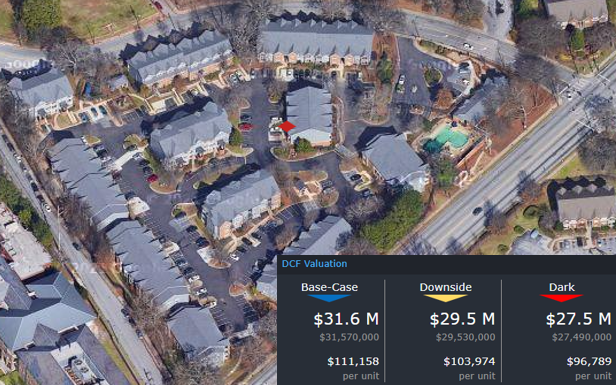
This $8.4 million loan, which is over 60 days delinquent, is secured by a 3-story, 284-unit multifamily property located in the Midtown West submarket of Atlanta, GA. The loan was originated by Prudential Huntoon Paige in December 2010. Mortgage financing was provided through the Section 221(d)(4) program as well as Section 223(a)(7), which provides refinancing of existing FHA loans. The loan has a 4.10% interest rate and became open to prepayment without penalty in January 2021. Maturity is scheduled for March 2039.
The mortgage collateral is Phase II of a larger 449-unit multifamily complex known as The Village at Castleberry Hill. Phase II was constructed in 2011 and benefits from a Low-Income Housing Tax Credit (LIHTC). Of the 284 units, there are 114 units set aside for rents equal to 50% of Area Median Income (AMI) or lower, 57 units with rents at 60% AMI or below, and 57 units with rents at 80% AMI or lower. There are 56 market rate units. The LIHTC presents affordable housing options in a central location within the Atlanta MSA. The collateral property is located in the Castleberry Hill neighborhood of Atlanta, and is adjacent to 3 universities — Morehouse College, Spelman College, and Clark Atlanta University — and is in close proximity to the Mercedes-Benz Stadium. Loan delinquency may be related to the need for rehabilitation for units requiring upgrades since loan origination was more than 10 years ago. For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including borrower contact information, sign up for a free trial here.
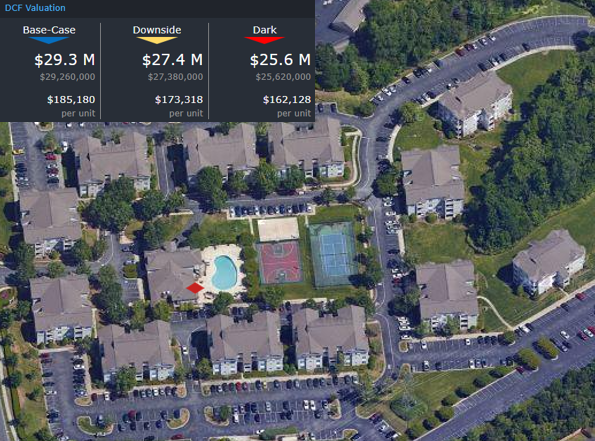
This $11.0 million loan, which is over 60 days delinquent, is secured by a 3-story, 158-unit student housing facility located in Charlotte, NC. The collateral provides housing to students enrolled at UNC Charlotte. Orix Real Estate Capital originated the loan in April 2012 under Section 221(d)(4) and 223(a)(7) programs. The loan’s prepayment penalty period will end in May 2022 and loan maturity is scheduled for May 2052. The prepayment penalty started at 8% and declined annually by 100 basis points. The interest rate is 3.19%.
The Latitude 49 Apartments, formerly known as 901 Place Apartments, were constructed in 2000 but have had several issues since initial development including bug infestations and break-ins. The property’s name was changed to ‘Latitude 49’ after a shooting on site in 2019 and the extended fallout of the event in the form of adverse impacts on leasing may be an underlying issue behind the loan’s delinquency. For full access to the valuation reports as well as full CMBS and GNMA loan reporting, including borrower contact information, sign up for a free trial here.
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. For full access to our loan database and valuation platform, sign up for a free trial below:
This week’s landscape takes us to the Delicate Arch in Moab, UT, a 52-foot natural freestanding stone arch, which is located 5 miles (33 miles driving distance) away from one of this week’s highlighted properties — Sorrel River Ranch.
This week, CRED iQ reviewed the commercial real estate lending landscape and highlighted 5 properties that have secured financing in the past month. The highlighted loan originations cover most property types (office, multifamily, industrial, lodging, and self-storage), giving a broad range of financing deals that have been completed. Notable among this group of recent mortgage originations is a hospitality loan – an uncommon occurrence given the operational struggles of lodging properties since the onset of the pandemic.
Using the CRED iQ platform’s Comps functionality, which features propriety Comps scoring for the CRE loan universe, we compared lending terms and loan structures to get a sense of the trends in the CRE lending environment. Additionally, we provided valuations for each asset to evaluate leverage levels in relation to originators’ LTVs. The CRED iQ valuations factor in a base-case (Most Likely), a downside (significant loss of tenants), and dark scenarios (100% vacant). Base-case valuations for select properties are provided below. For full access to the valuation reports as well as full CMBS loan reporting, including detailed financials, updated tenant information, and borrower contact information, sign up for a free trial here.
399 Jefferson Road
206,155 sf, Office, Parsippany, NJ
Prism Capital Partners secured a $37 million loan from KeyBank on October 26, 2021 to refinance existing debt of $35.4 million. The loan was structured with a 10-year term, an interest rate of 4.19%, and an amortization schedule of 30 years. The loan will be locked out from prepayment for 2 years, and defeasance will be permitted after lockout through the remainder of the term. One of CRED iQ’s most relevant comps for this new origination is a $62.4 million loan, which was originated on September 15, 2020 and has an interest rate equal to 1-month LIBOR + 4.75%. The comparable loan is secured by a portfolio of 10 office properties located throughout Parsippany, NJ with an average building size of approximately 165,000 sf.
The 399 Jefferson Road mortgage loan is secured by fee interest in a single-story, 206,155-sf office property located in Parsippany, NJ. The property, which contains about 75% office space and 25% R&D space, is 100% leased between two tenants — Remarkable Foods (50% of the GLA) and Zimmer Biomet (50% of the GLA). At loan origination, Remarkable Foods was subleasing its space from Conagra Brands but is committed to a direct lease that takes effect in April 2023. The Remarkable Foods direct lease expires in April 2031 (with 2, 5-year extension options) and the Zimmer Biomet lease expires in July 2028 (with 2, 5-year extension options). The two tenants’ lease expirations, both of which occur prior to loan maturity in November 2031, will be the primary credit events during the loan’s term, absent any tenant bankruptcy action.
The property was appraised at a value of $54.4 million, equal to $264/sf, as of August 13, 2021, which implied an LTV of 68% and a capitalization rate of 6.05% based on the originator’s underwritten NCF. For the full valuation report and loan-level details, click here.
Subject Property
BBCMS 2021-C12
Name
399 Jefferson Road
Address
399 Jefferson Road Parsippany, NJ 07054
Property Type
Office
Property Subtype
Suburban
Building Size
206,155 sf
Year Built
1968
Submarket
Parsippany-Troy Hills
County
Morris
MSA
New York-Northern New Jersey-Long Island, NY-NJ-PA
Origination Date
10/26/2021
Loan Amount
$37,000,000
Interest Rate
4.19%
Valuation
Appraised Value
$54,400,000 ($264/sf)
Appraisal Date
8/13/2021
Appraisal LTV
68.00%
CRED iQ Base-Case Value
$49,730,000 ($241/sf)
445 Vanderbilt
43 units, Multifamily, Brooklyn, NY
A $22 million loan was originated by Société Générale on October 28, 2021 to refinance existing debt of $16.1 million and return approximately $5.2 million in equity to loan sponsors Pinny Loketch and Allan Lebovits. The interest-only loan was structured with a 10-year term and an interest rate of 3.6625%. The loan will be locked out from prepayment for 2 years, and defeasance will be permitted after lockout through the remainder of the loan term. The newly originated mortgage represents financing on an asset with limited operational history given the collateral was developed within the past year; however, terms of the loan appear to be in line with CRED iQ’s comps database. As an example, Greystone originated a $23.5 million 10-year loan in January 2020 that is secured by a 33-unit multifamily property located about 2 blocks away from 445 Vanderbilt. The interest rate for the comparable loan was 3.49% with an amortization schedule of 30 years.
The 445 Vanderbilt mortgage loan is secured by fee interest in a 5-story, 43-unit multifamily property located in the Clinton Hill submarket of Brooklyn, NY. The property was developed in 2021, along with several adjacent townhouses that do not serve as collateral for the mortgage loan. Of the 43 units, there are 13 affordable housing units as required by the property’s 421-a (16) tax exemption, which provides for 35 years of post-construction tax benefits. The 421a affordable units may be rented to tenants at 130% of area median income (AMI). As first reported by New York YIMBY, a lottery for the affordable housing units occurred in August 2021.
The property was appraised at a value of $33 million, equal to $767,442/unit, on September 15, 2021, which resulted in an LTV of 67% and an implied cap rate of 4.43% based on the originator’s underwritten NCF. CRED iQ calculated a value assuming the fully unabated real estate tax for the property. For the full valuation report and loan-level details, click here.
Subject Property
BBCMS 2021-C12
Name
445 Vanderbilt
Address
445 Vanderbilt Avenue Brooklyn, NY 11238
Property Type
Multifamily
Property Subtype
Mid Rise
Building Size
43 units
Year Built
2021
Submarket
Clinton Hill
County
Kings
MSA
New York-Northern New Jersey-Long Island, NY-NJ-PA
Origination Date
10/28/2021
Loan Amount
$22,000,000
Interest Rate
3.66%
Valuation
Appraised Value
$33,000,000 ($767,442/unit)
Appraisal Date
9/15/2021
Appraisal LTV
66.70%
CRED iQ Base-Case Value
$25,320,000 ($588,806/unit)
Glendale Industrial
129,326 sf, Industrial, Los Angeles, CA
A $20 million loan was originated by Starwood Mortgage Capital on October 29, 2021 to refinance existing debt on a 129,326-sf industrial flex property located in the Frogtown submarket of Central Los Angeles, CA. The loan was structured with a 10-year term, an interest rate of 4.80%, and a two-year interest-only period. The loan would require a yield maintenance charge for prepayment, which is permitted after a 6-month lockout period.
The mortgaged property is a former Hostess bakery that was repositioned as industrial flex space in 2013 and includes an adjacent parking lot. The property is 100% leased to Academy Film Studios through September 2036, which is nearly 5 years beyond loan maturity. The tenant is affiliated with the loan’s sponsor, Frank Novak, owner of Modernica Props.
The property was appraised at a value of $38.7 million, equal to $299/sf, as of July 14, 2021. However, the NNN master lease with the property’s single tenant yielded a slightly lower appraisal based on contracted rent, which was deemed to be below market. CRED iQ’s Comp Set Average Rent for the property was $14.67/sf. The as-is appraisal at origination implies an LTV of 52% and an implied cap rate of 4.16%. For the full valuation report and loan-level details, click here.
Subject Property
BBCMS 2021-C12
Name
Glendale Industrial
Address
2330 Ripple Street Los Angeles, CA 90039
Property Type
Industrial
Property Subtype
Flex
Building Size
129,326 sf
Year Built
1935
Submarket
Frogtown
County
Los Angeles
MSA
Los Angeles-Long Beach-Santa Ana, CA
Origination Date
10/29/2021
Loan Amount
$20,000,000
Interest Rate
4.80%
Valuation
Appraised Value
$38,720,000 ($299/sf)
Appraisal Date
7/14/2021
Appraisal LTV
51.65%
CRED iQ Base-Case Value
$37,140,000 ($287/sf)
Sorrel River Ranch
56 rooms, Full-Service Hotel, Moab, UT
Commercial mortgage originations secured by lodging properties have been rare sightings in 2021. This $19 million loan was provided by Starwood Mortgage Capital on October 29, 2021 to provide refinancing for existing debt on the Sorrell River Ranch Resort and Spa. The interest-only loan has a 10-year term and an interest rate of 4.02%. The loan will be locked out from prepayment for 2 years, and defeasance will be permitted after lockout through the remainder of the loan term. Due to the nature of the collateral, the loan was also structured with a seasonality reserve that had a balance of approximately $576,000 at origination. Comparable loans were limited based on property type and location of the collateral; however, this mortgage origination is a prime example of the types of lodging deals that are getting completed in the current landscape.
Perhaps best known for providing guests the option of arriving at the resort via skydiving adventures, the Sorrel River Ranch has 56 rooms across 11 acres in Moab, UT, along the banks of the Colorado River. Average occupancy for the resort was 42% for the trailing 12 months ended August 31, 2021. The ADR and RevPAR for the same period were $1,116 and $469, respectively. The property was appraised at a value of $42.0 million, equal to $750,000 per room, as of October 1, 2021, which resulted in an LTV of 42%. The originator’s underwritten net cash flow for the property implied a cap rate of 9.89%. For the full valuation report and loan-level details, click here.
Subject Property
BBCMS 2021-C12
Name
Sorrel River Ranch
Address
17 Utah 128 Moab, UT 84532
Property Type
Hotel
Property Subtype
Resort
Building Size
56 rooms
Year Built
1999
Submarket
Moab
County
Grand
MSA
Non-Metropolitan Area-UT
Origination Date
10/29/2021
Loan Amount
$19,000,000
Interest Rate
4.02%
Valuation
Appraised Value
$42,000,000 ($750,000/room)
Appraisal Date
10/1/2021
Appraisal LTV
42.20%
CRED iQ Base-Case Value
$38,960,000 ($695,797/room)
Fort Storage – Milton, FL
100,105 sf, Self Storage, Milton, FL
KeyBank provided $8.0 million in financing on October 26, 2021 to pay off existing debt on a 100,105-sf self-storage property located in Milton, FL. The interest-only loan had a term of 5 years with an interest rate of 4.42%. One of CRED iQ’s highest rated comps for this new origination is a $6.9 million loan that is secured by a 57,848-sf self-storage facility located further east on the Florida Panhandle. This comparable loan was originated on July 2, 2020 and had an interest rate of 4.34%.
Fort Storage is a self-storage facility in Milton, FL, located about 20 miles northeast of Pensacola. The facility offers a variety of unit configurations, including climate-controlled solutions, ranging in size from 5×5 feet to 20×30 feet. The property was 97% occupied as of October 19, 2021 and was appraised for $15.9 million as of August 2, 2021, which was equal to an LTV of 50%. Based on the originator’s underwritten net cash flow, the implied cap rate for the property was 4.57%. For the full valuation report and loan-level details, click here.
Subject Property
BBCMS 2021-C21
Name
Fort Storage
Address
4114 Avalon Boulevard Pensacola, FL 32583
Property Type
Self Storage
Property Subtype
Self Storage
Building Size
100,105 sf
Year Built
2006
Submarket
Pensacola
County
Santa Rosa
MSA
Pensacola, FL
Origination Date
10/27/2021
Loan Amount
$8,000,000
Interest Rate
4.42%
Valuation
Appraised Value
$15,860,000 ($158/sf)
Appraisal Date
8/2/2021
Appraisal LTV
50.40%
CRED iQ Base-Case Value
$15,530,000 ($155/sf)
CRED iQ is a commercial real estate data, analytics, and valuation platform providing actionable intelligence to CRE and capital markets investors. Subscribers to CRED iQ use the platform to identify valuable leads for leasing, lending, refinancing, distressed debt, and acquisition opportunities. For full access to our loan database and valuation platform, sign up for a free trial below: