Both Chicago teams made October. Chicago’s office towers didn’t. How commercial real estate is holding up in the 11 playoff metros.
In July, the $536 million loan on Chicago’s Aon Center reached maturity and wasn’t repaid. The tower, appraised at $824 million when the loan was securitized, is now valued at $195 million. A three-year extension request “was unequivocally denied,” according to servicer commentary.
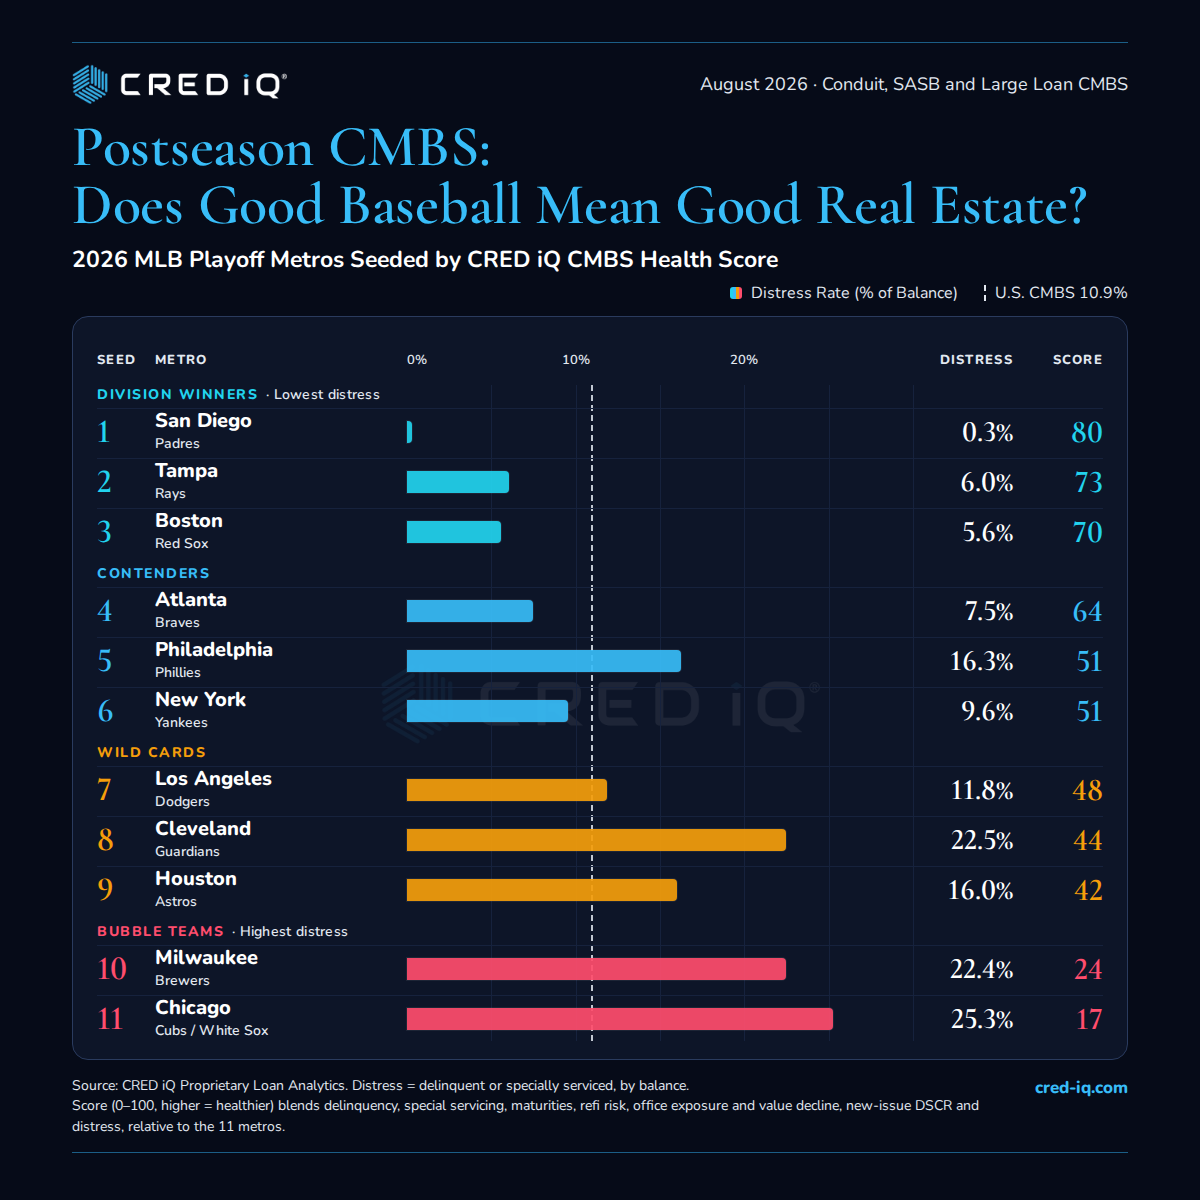
Chicago is the weakest real estate market in this year’s postseason. As of August, 25.3% of Chicago’s outstanding CMBS balance was delinquent or in special servicing, according to CRED iQ. That is the highest of the 11 playoff metros and up 4.7 percentage points in a year.
Nationally, the CMBS distress rate was 10.9% in August, down from 11.5% a year earlier. Preliminary September numbers point to a similar 10.8%. The steady headline masks office, which accounts for 45.5% of distressed balance and whose distress rate climbed to 16.0%. Office is the top source of distress in eight of the 11 playoff metros.
| Metro | Team(s) | Distress Rate | Change vs. Aug 2025 | Primary Driver |
|---|---|---|---|---|
| San Diego | Padres | 0.3% | −0.8 pts | None (all types under 2%) |
| Boston | Red Sox | 5.6% | +0.1 pts | Mixed-use / life science |
| Tampa | Rays | 6.0% | −1.4 pts | Retail |
| Atlanta | Braves | 7.5% | −6.7 pts | Office |
| New York | Yankees | 9.6% | −2.9 pts | Office |
| Los Angeles | Dodgers | 11.8% | +3.5 pts | Office |
| Houston | Astros | 16.0% | +3.3 pts | Office |
| Philadelphia | Phillies | 16.3% | −0.2 pts | Office |
| Milwaukee | Brewers | 22.4% | +2.7 pts | Office |
| Cleveland | Guardians | 22.5% | +2.4 pts | Office |
| Chicago | Cubs, White Sox | 25.3% | +4.7 pts | Office |
| U.S. CMBS | 10.9% | −0.5 pts | Office |
The bottom of the bracket
Cleveland (22.5%) and Milwaukee (22.4%) join Chicago at the bottom. In Cleveland, $414 million of distressed debt sits within a mile of Progressive Field, led by Key Center, in special servicing since 2020. Milwaukee’s distress centers on Southridge Mall, where the value has fallen 74%.
The middle innings
Philadelphia (16.3%) is weighed down by three loans on Market Street West, at 1500, 1700 and 1818 Market, totaling $779 million and 40% of the metro’s distress. Houston (16.0%) rose 3.3 points as One & Three Allen Center, a $470 million loan on a 71%-occupied complex, moved to special servicing and six apartment loans became distressed this summer. Los Angeles (11.8%) jumped in August when the $1.1 billion ICON/Hollywood Media Portfolio loan transferred ahead of maturity; 20 LA loans totaling $2.5 billion became distressed this summer.
The comeback stories
New York’s rate fell 2.9 points to 9.6% as $6.1 billion of loans cured, including 1211 Avenue of the Americas ($1.035 billion) and One New York Plaza ($810 million). Worldwide Plaza, with its value down 74%, remains the biggest problem. Atlanta fell to 7.5% from 14.2%, helped by the payoff of a $580 million hotel portfolio loan.
The top seeds
San Diego is the cleanest market in the postseason at 0.3% distressed, with the Hotel del Coronado and a 98%-occupied Fashion Valley mall among its largest loans. In Tampa (6.0%), one asset, the 27%-occupied Westfield Countryside mall, accounts for 62% of distress. Boston (5.6%) is dominated by a single life-science loan that remains current.
The takeaway
The national rate is an average of very different markets. Midwestern office cores are still deteriorating, New York is healing, and in the healthiest cities a few buildings decide the score. For lenders, the question isn’t who wins the pennant. It’s which loans come due next.
Source: CRED iQ proprietary loan-level analytics, August 2026. Conduit and SASB/SBLL CMBS. Distress rate is the share of outstanding balance that is delinquent or in special servicing. September 2026 figures are preliminary.